BILL AP & AR Business Payments
Bill.com Inc.
- 4.3
- 1.54K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
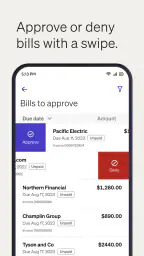
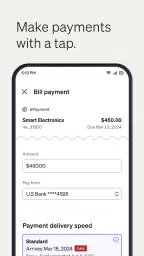
BILL AP & AR Business Payments Pros and Cons
Pros
- Streamlines invoice creation, tracking, and payment collection in one app.
- Helps reduce manual entry with organized customer and invoice records.
- Provides useful visibility into outstanding receivables and payment status.
- Supports faster communication with customers about invoices and due dates.
- Can improve cash-flow management for small businesses and freelancers.
Cons
- Some advanced features may require a paid subscription or upgraded plan.
- Initial setup can take time when importing customers and existing invoices.
- The app may feel complex for users handling only occasional invoices.
- Payment availability and fees can vary by country and supported provider.
- Businesses may need another accounting tool for deeper financial reporting.
 Analysis by All-app
When a small business owner tells me that paying bills takes longer than the work that created them, I usually understand the frustration. Invoices arrive through different channels, approvals happen in scattered conversations, and it is easy to lose track of what has been paid or what still needs attention. BILL AP & AR Business Payments is built for that part of business life: handling accounts payable and accounts receivable through an online payment workflow rather than treating every transaction as a separate manual task.
I reviewed it as a business app from Bill.com Inc., and my first impression was that it is aimed at people who need structure more than they need another general banking app. It is free to install, rated for Everyone, and has been available since Dec 16, 2015. The current release is version 3.7.171, with a minimum operating system requirement of iOS 9. That broad compatibility makes it approachable for teams using older Apple devices, although the age of the platform requirement should not be confused with a promise that every modern workflow will feel equally polished on every device.
The useful question is not whether the app can move money online; it is whether it can make the path from incoming bill to completed payment easier to control. In my experience, that is where its value becomes clear. It can help a business turn a loose collection of bills, customer payments, and internal decisions into a process that is easier to follow. It is less compelling if you only need to send an occasional payment or if your business already has a complete accounting system that handles every approval and reconciliation task comfortably.
Following a business payment from arrival to completion
When I follow a business payment from its arrival to its completion, I pay attention to more than the transfer itself: I want to know who supplied the details, who checked them, and what still needs follow-up. That end-to-end view is especially useful when several people share responsibility for bills and customer payments. Next, I’ll look at how to set sensible boundaries around that shared workflow.
Beginning with the messy part: bills, invoices, and pending decisions
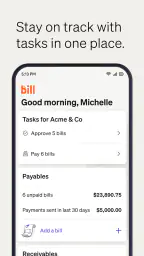
A realistic use case is a small agency with several recurring suppliers, a few contractors, and customers who pay against invoices. Before using a dedicated accounts payable and receivable workflow, the owner may keep bills in email, save attachments in folders, and mark payments in a spreadsheet. That arrangement can work for a while, but it becomes fragile when another person needs to review a payment or when the owner is away from the office.
This is where I would place BILL AP & AR in the process. Rather than opening a consumer banking app and dealing with each payment as an isolated event, I would use it as the business payment workspace. The important mental shift is that a bill is not just a transfer of money. It also has a supplier, an amount, a reason, a timing decision, and often another person who needs to approve it.
For accounts receivable, the starting condition is reversed. The business has done the work and needs to collect money from a customer. Managing that side alongside outgoing bills is practical for owners who want a clearer view of cash moving in both directions. It does not eliminate the need for good invoicing habits, but it can reduce the temptation to treat customer collections and supplier payments as unrelated administrative chores.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Preparing the payment instead of rushing to send it
My preferred workflow would begin by reviewing the bill or invoice carefully before entering a payment. I would check the supplier or customer, confirm the amount, look at the due date, and make sure the transaction belongs to the correct business activity. That sounds obvious, yet this is exactly where rushed phone-based administration causes mistakes. A convenient app cannot correct an incorrect amount or a duplicate request that was never checked.
The advantage of a dedicated business payment tool is that it encourages a deliberate sequence. I can prepare the transaction, inspect the details, and then move it forward rather than switching repeatedly between email, notes, and a bank screen. For a busy owner, that reduction in context switching is a real benefit. The time saved is not only the time spent tapping; it is also the time spent remembering what has already been handled.
One practical habit I found valuable is separating preparation from final authorization whenever the business has more than one person involved. An employee can gather the information and make the payment ready for review, while the owner or manager retains the final decision. This creates a useful handoff instead of forcing one person to perform every step from data entry to approval.
Managing handoffs between the person who prepares and the person who approves
Handoffs are where many small-business processes become unclear. An assistant may say that a bill is ready, while the owner assumes it was already paid. A contractor may send an invoice twice because there was no visible status. A customer payment may arrive without enough context to connect it to the right invoice. The value of BILL AP & AR is strongest when the team uses it as a shared process rather than as a private shortcut for one individual.
I would recommend agreeing on a simple internal routine before inviting other people into the workflow. Decide who prepares transactions, who checks them, and who confirms the result. The app can support the movement of a payment through those stages, but it cannot create accountability by itself. If nobody knows who owns the next action, a digital queue can become just another place where work waits.
There is also a trade-off here. A structured approval path may feel slower than immediately paying a supplier from a bank account. That extra step is worthwhile for recurring bills, larger expenses, or payments that need a second pair of eyes. It may feel excessive for a sole proprietor who pays only a handful of predictable expenses and has no internal handoff at all.
For that reason, I would not recommend forcing every transaction through the same level of review. Routine, familiar bills can follow a quick check, while unusual amounts or new payees deserve more attention. The app is most useful when it gives a business a consistent place to make that distinction.
Keeping accounts payable and accounts receivable in the same conversation
The combined AP and AR focus is more meaningful than it first appears. A business can look profitable on paper and still feel short of cash if supplier payments leave the account before customer invoices are collected. Looking at outgoing and incoming payments as connected parts of the same operating cycle helps an owner make better timing decisions.
Imagine a design studio waiting for a customer to pay an invoice while a software supplier and a freelance specialist are both due. The owner may not want to delay legitimate payments, but needs to understand the order of events. A business payment app cannot manufacture cash, yet it can make the commitments and collections easier to organize. That is a more useful role than pretending payment administration is separate from cash-flow planning.
My tip is to review incoming and outgoing work together at a regular time rather than checking them only when something becomes urgent. Use the outgoing side to identify commitments and the incoming side to identify expected collections. Then decide which items need action today and which can remain scheduled for later attention. This turns the app from a transaction button into a lightweight operating routine.
What the recipient or customer experiences
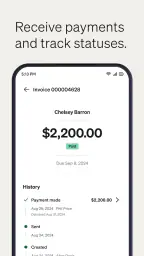
A payment workflow is not complete when the sender taps a confirmation control. The recipient needs a clear outcome, and the business needs a record that can be understood later. For suppliers, that may mean knowing that a bill has moved beyond internal review. For customers, it may mean having a straightforward way to settle an invoice without a long email exchange.
This is one reason I prefer a purpose-built business payment environment over relying entirely on personal banking tools. A normal banking app is excellent for moving money from one account to another, but it usually does not represent the surrounding business context as clearly. The business user is not only asking, “Did money leave?” They are asking, “Which obligation did it satisfy, who approved it, and what still needs follow-up?”
At the same time, the app should not be treated as a replacement for every customer communication. If an invoice is disputed, incomplete, or missing supporting information, sending a payment will not solve the underlying issue. I would resolve the commercial question first and use the payment workflow once the amount and purpose are agreed.
Reaching the result: less uncertainty, not just a completed transfer
The best outcome is not merely that a payment was sent. It is that the business can tell what happened without reconstructing the story from memory. A completed transaction should leave the owner more confident about which bills are settled, which customer payments have arrived, and which items still require action.
That is where the app feels most appropriate for growing businesses. It offers a more organized path than a personal finance tool, while remaining more focused than a large accounting suite that may require extensive setup and training. I would describe it as a bridge between informal administration and a more disciplined financial operation.
The audience response suggests that this positioning works for many people. BILL AP & AR holds an average rating of 4.3 from around 7,500 ratings, with roughly 1,500 written reviews, and it has passed 500,000 installs. Those figures do not guarantee that it will fit every company, but they indicate that the app has attracted a substantial audience beyond a handful of early adopters.
Where the workflow breaks down
The first weakness is that organization depends on adoption. If one employee continues approving bills by email, another uses a spreadsheet, and the owner pays directly through a bank app, the central workflow loses its value. The app can provide a place for the process, but the team still has to agree to use that place consistently.
The second limitation is that mobile convenience can encourage shallow checking. A small screen is fine for reviewing a familiar payment, but less comfortable when comparing several invoice details, investigating an unfamiliar charge, or handling a complicated exception. I would use the phone for monitoring, quick review, and time-sensitive actions, while reserving more involved cleanup for a larger screen or a calmer work session when possible.
Another point of friction is the difference between payment processing and accounting control. Businesses often need detailed categorization, tax treatment, reconciliation, reporting, and historical analysis. A payment-focused app can be an important part of that chain, but it should not automatically be assumed to replace the company’s accounting platform. If your accountant depends on a particular ledger structure, confirm that the workflow you choose will not create extra manual work later.
There is also a human limitation: approvals can become a bottleneck. A second review improves control, but if the approver is unavailable and there is no agreed backup, urgent payments may wait. Before relying on the app for critical deadlines, I would establish who can act when the usual reviewer is traveling, ill, or simply overwhelmed.
How it compares with familiar alternatives
The usual alternative for a very small business is a bank app plus email and a spreadsheet. That combination is inexpensive and familiar, and it may be enough for a freelancer with few transactions. Its weakness is the handoff: the payment may be visible in the bank account, but the surrounding approval and invoice context can remain scattered.
Another alternative is a full accounting package. That route is stronger when the business needs deep bookkeeping, reports, tax preparation support, and a complete financial record in one environment. The trade-off is complexity. A company that mainly wants a cleaner way to handle bills and customer payments may find a large accounting system heavier than necessary.
BILL AP & AR sits between those choices. It is more structured than a bank-only routine and more focused than a broad accounting platform. I would choose it for a small team that is beginning to outgrow informal processes but does not want payment administration to become a major software project. I would look elsewhere if the main requirement is advanced accounting analysis rather than payment coordination.
Who should install it, and who should skip it
I think the app is a good match for owners, office managers, and small finance teams that handle both supplier bills and customer collections. It is especially useful when more than one person touches a transaction, because a visible workflow is more valuable as soon as preparation and approval are separated.
It can also suit a business owner who works away from a desk and needs to keep payment tasks moving from a phone. The free price makes it easy to try without treating installation as a major financial commitment, and the Everyone content rating makes it broadly accessible from an age-classification standpoint.
I would skip it if you only make occasional personal payments, if your business has no recurring bills to organize, or if your existing accounting environment already gives you a smooth AP and AR process. I would also hesitate if your team is unwilling to change its habits. In that situation, adding another app may increase duplication instead of reducing it.
Small habits that make the workflow safer and clearer
First, I would avoid approving a payment from a notification alone. Open the transaction and check the underlying details, particularly when the amount or recipient is unusual. Notifications are useful prompts, but they are not a substitute for review.
Second, I would create a short weekly routine for unresolved items. Look for bills waiting on approval, customer invoices that still need attention, and transactions whose purpose is unclear. This catches stalled handoffs before they become late fees, awkward supplier calls, or unnecessary follow-up messages.
Third, I would use a two-person check for changes that matter, such as a new supplier or an unexpected invoice. The extra pause is a trade-off, but it is more valuable on exceptional transactions than on familiar recurring expenses. This is a practical way to preserve speed without treating every payment as equally risky.
Finally, I would compare the app’s payment activity with the business’s accounting records on a regular schedule. That simple reconciliation habit protects against the false comfort of seeing a completed action inside one system while another record remains outdated. The app can make the payment trail clearer, but the business still needs a dependable financial close process.
My overall experience with the mobile approach
What I like most is the way the app frames payment work as a process with a beginning, a review stage, and an outcome. That is more useful than a bare transfer screen when bills and invoices pass between people. The AP and AR combination also encourages a healthier view of cash movement, where paying suppliers and collecting from customers are part of one operating picture.
What I like less is the risk of expecting a mobile payment tool to solve broader operational problems. It cannot decide whether an invoice is legitimate, negotiate a disputed charge, or replace thoughtful bookkeeping. Its success depends on clear internal ownership and on users taking a moment to verify what they are approving.
Overall, I would recommend BILL AP & AR to a small business that has reached the point where email, spreadsheets, and direct bank payments are becoming difficult to coordinate. Its strongest use case is a repeatable workflow with real handoffs: someone prepares the transaction, someone reviews it, and the business can later understand the result. For a simple personal payment or a company already well served by a full accounting system, another option may be more efficient.
For the right user, the app’s main benefit is not flashy functionality. It is the quiet reduction of uncertainty around everyday business payments. If that is the problem you are trying to solve, I think this free business app is worth testing as a more disciplined home for accounts payable and accounts receivable.
Frequently Asked Questions
What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is a business finance platform designed to help companies manage accounts payable and accounts receivable in one place. After reviewing its main functions, the app appears focused on paying vendor bills, sending invoices, tracking payment status, organizing financial workflows, and reducing manual administrative work for small and midsize businesses.
Can I use BILL to pay bills and manage vendor payments?
Yes. The platform is built to support accounts payable tasks, including organizing bills, scheduling payments, and keeping a record of completed or pending transactions. Depending on your account type and payment method, businesses may be able to pay vendors by electronic transfer, card, or check. Available options, processing times, and fees can vary, so reviewing the payment details before confirming is important.
Does BILL AP & AR support invoicing and receiving customer payments?
BILL also includes accounts receivable tools intended to help businesses create and send invoices, monitor outstanding balances, and accept customer payments. This can be useful for companies that want to connect billing and payment tracking with their broader financial workflow. Certain features may depend on the subscription plan, customer setup, supported payment methods, or integration with compatible accounting software.
Is BILL AP & AR safe for business payments and financial information?
Because the app handles invoices, payment details, and sensitive business data, security is an important consideration. BILL uses account authentication and security controls intended to protect users and transactions, but no online service can eliminate every risk. Businesses should use strong, unique passwords, enable available security features, limit user permissions, and verify payment instructions before sending money.
Does BILL AP & AR integrate with accounting software, and is it easy to use?
BILL is designed to work alongside common business accounting workflows, which can help synchronize bills, invoices, payment records, and financial information with supported accounting platforms. In testing, the interface is most useful for teams that already have organized approval and bookkeeping processes. However, setup may require administrator permissions, account configuration, and some learning before the workflow feels completely efficient.